Scopevest
AI investment research for China's A-shares, with every strategy tested out of sample.
What it is
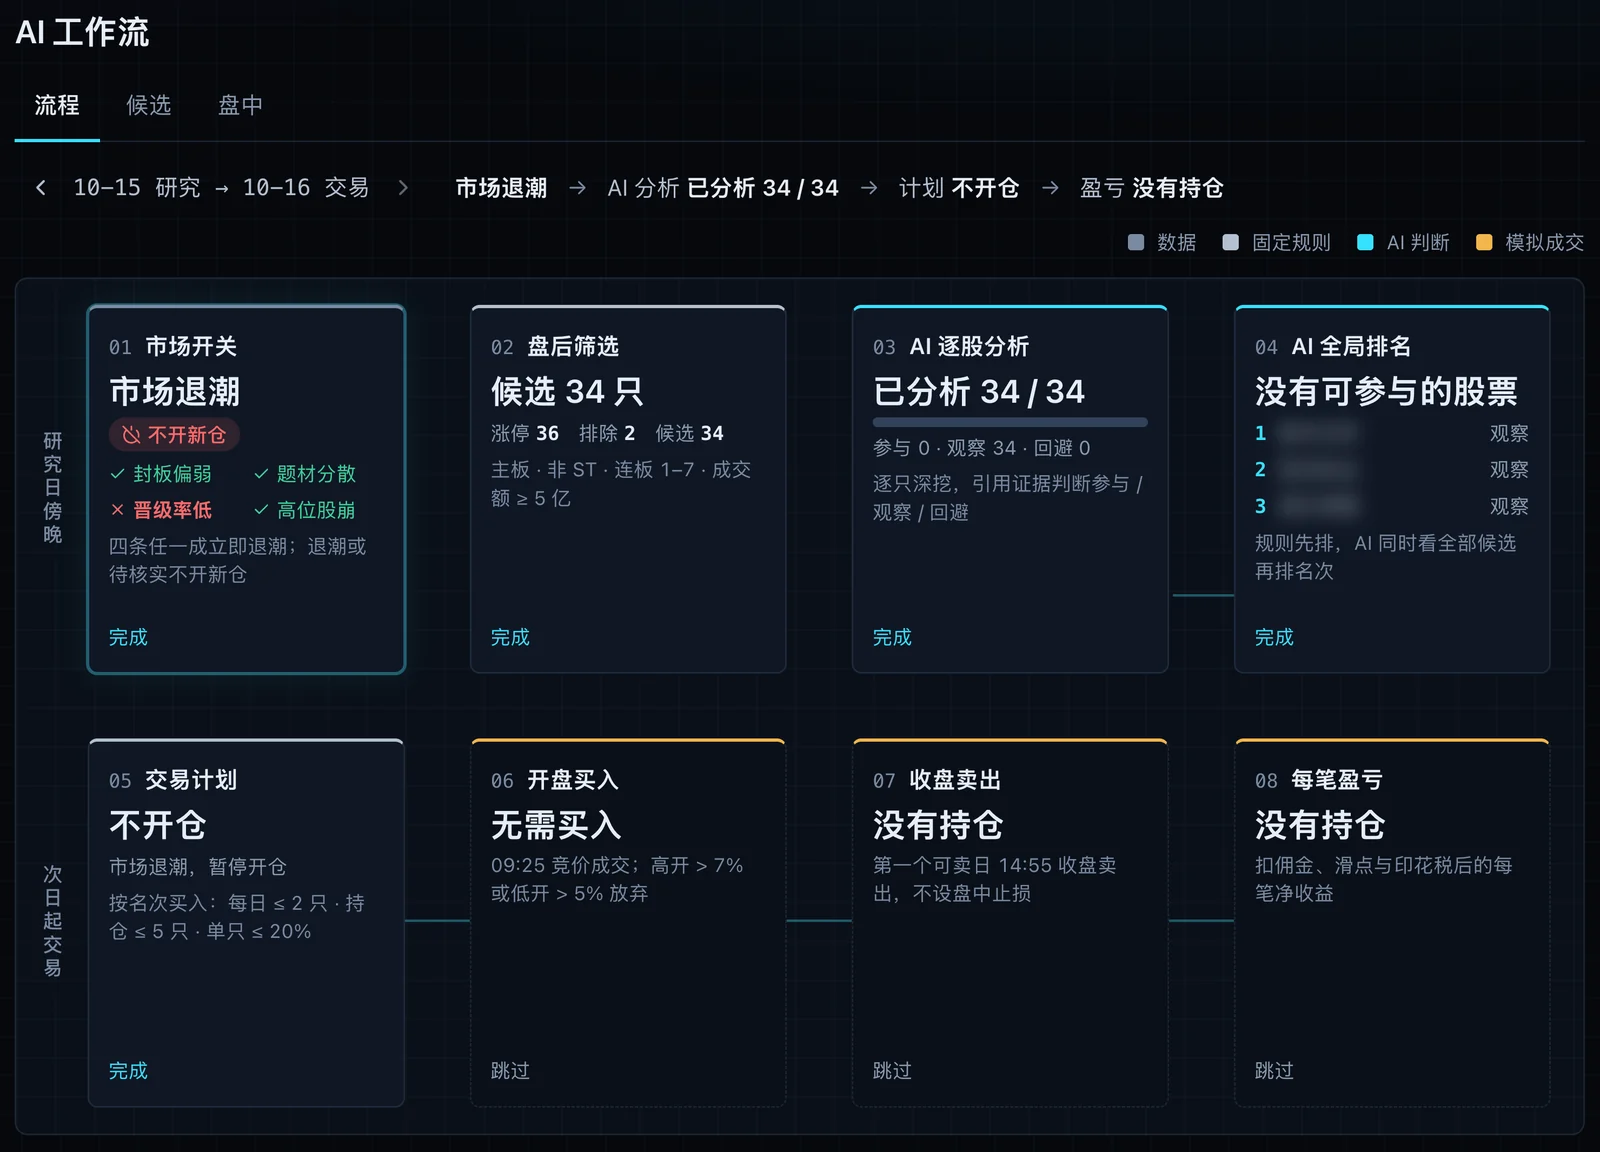
Scopevest (观衡) is an AI research workspace for China’s A-share market. It gathers daily prices, fund flows and limit-up data, has a language model write a research judgment for each stock, and records the evidence behind it and the conditions that would prove it wrong. An AI paper-trading account follows those judgments with fixed rules. It never connects to a broker.
The question
Earlier versions came with impressive numbers: one limit-up rule set claimed +54% a year from a three-month backtest of 140 trades. A strict reproduction came in lower, and 27.7% of 1,000 random portfolios did better. Before putting real money behind anything, I wanted to know which of those claims survive a proper test.
How it was tested
- Every hypothesis and parameter was written down and committed before the run (pre-registration), so results couldn’t be picked after the fact.
- Long samples: 116,563 limit-up events from 2016 to 2026, monthly portfolios back to 2010, with separate training and test periods.
- Real trading constraints: buy at the next open, no fill when it opens limit-up, T+1, and about 0.3 percentage points in round-trip costs.
- Multiple-testing corrections, with every run counted as a trial.
What we found
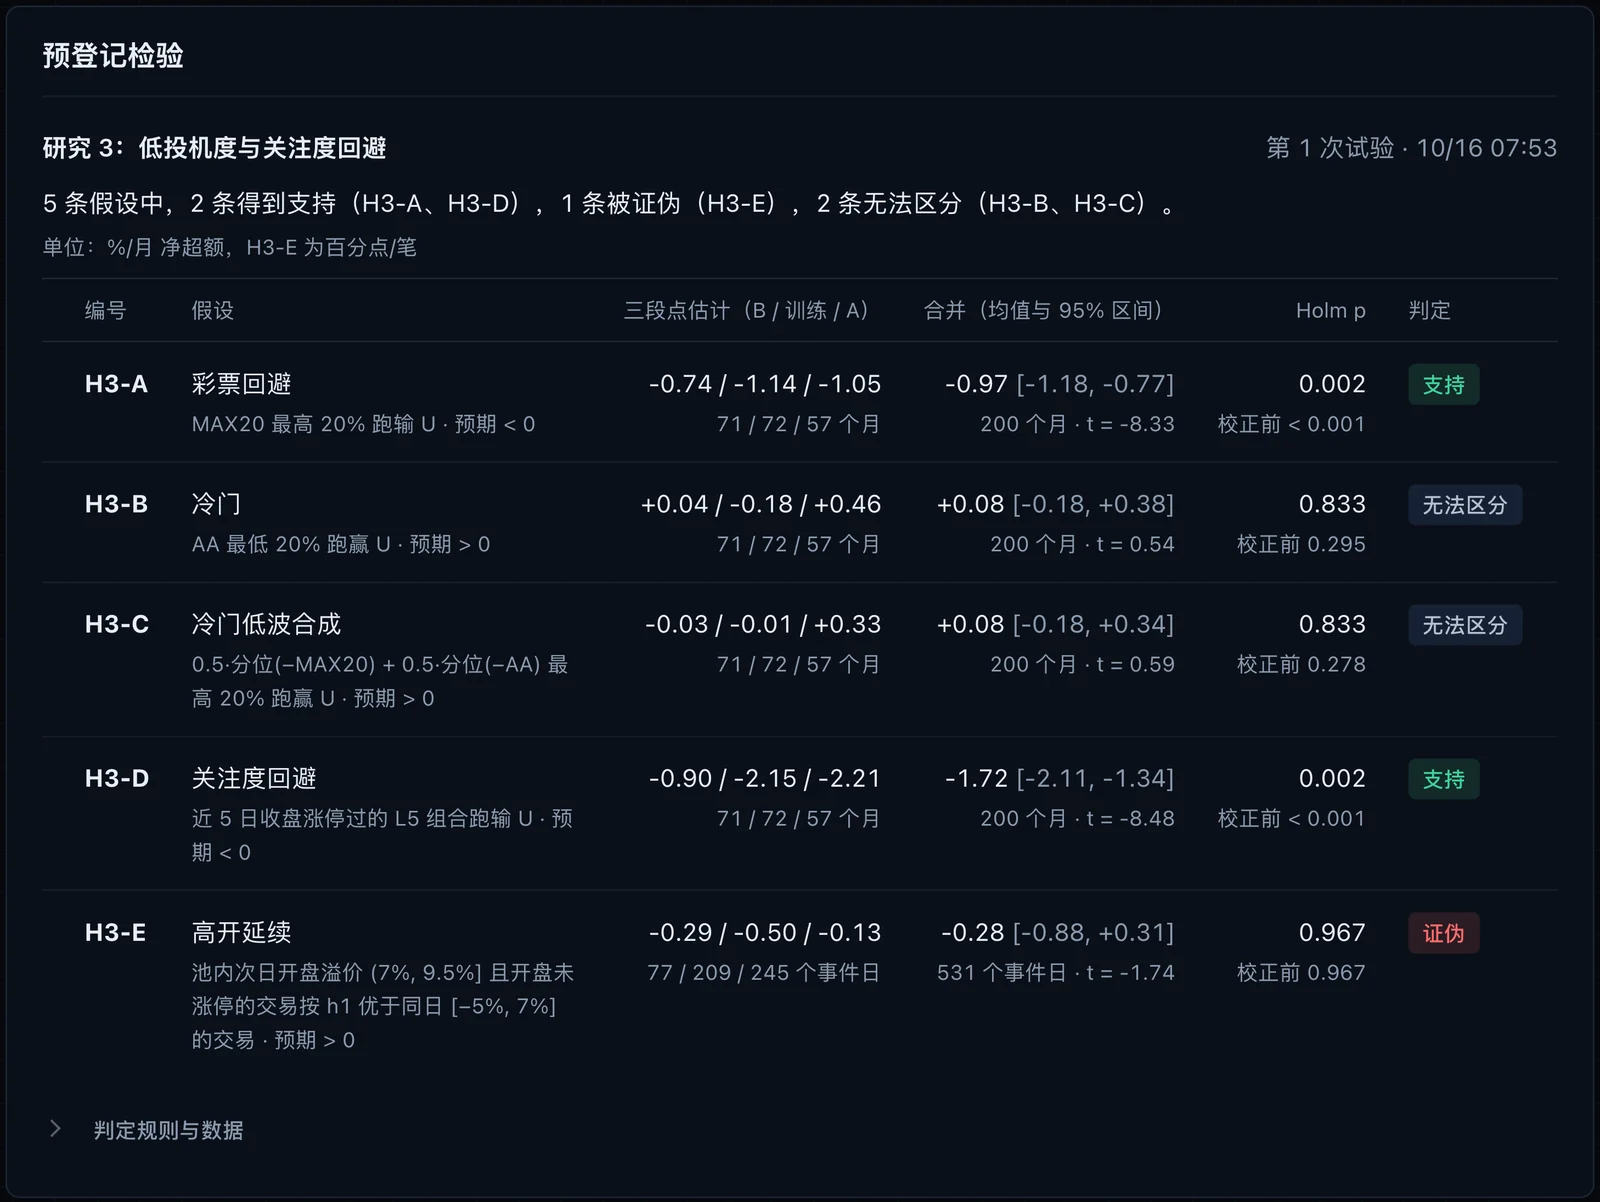
Long-only, daily data, public information: none of the speculative strategies we proposed made money after costs out of sample. Buying a limit-up stock at the next open loses about 1% to 1.4% per trade. The “2–3 consecutive limit-ups” rule that looked best over three months did 0.90% per trade worse than other limit-up stocks on the same day across ten years. Technical scores and multi-timeframe signals that worked in training reversed in testing, and news used as a direction signal did no better than a placebo.
What held up was a list of things not to do:
- Don’t chase limit-up stocks at the next day’s open.
- Don’t buy lottery-like stocks; they lag by about 1% a month.
- Don’t buy stocks that hit limit-up in the past five days; they lag by about 1.7% a month.
- Don’t chase prominent good news such as contract wins.
What I take from it
- Limit-ups, streaks and headline announcements are where the market’s attention is most crowded. Faster, better-funded traders sit on the other side, and whoever buys at the next open pays for it.
- Complexity didn’t create an edge. Better prompts and more indicators can’t get past the limit of public information.
- The most valuable output is the method: pre-registration, out-of-sample tests, real costs and fixed decision deadlines. It kept me from putting money behind a strategy that only looked good for three months.
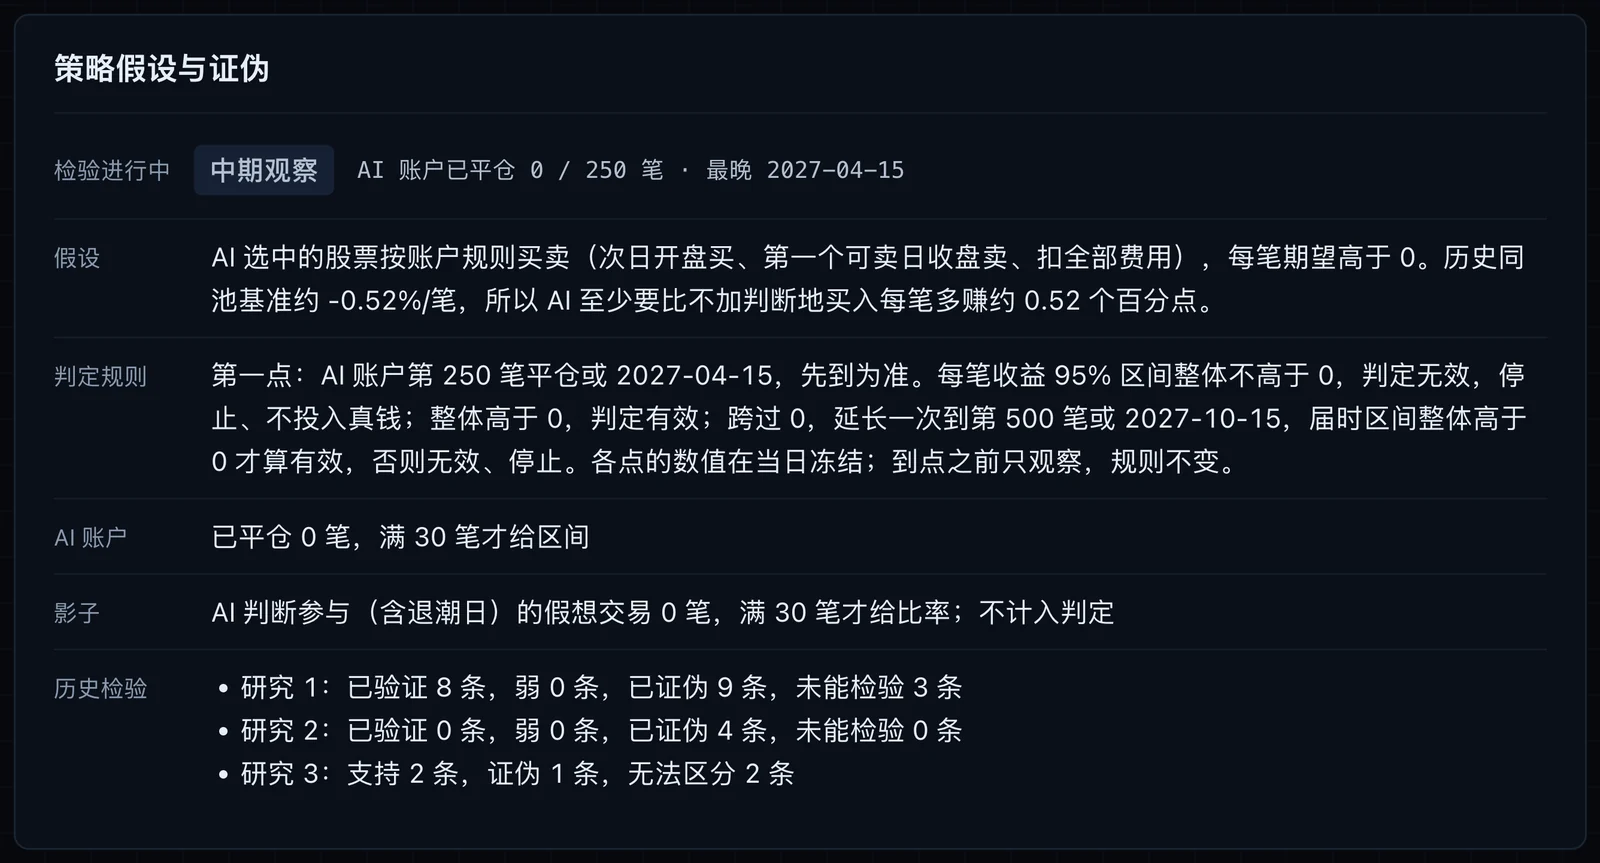
The AI paper-trading account keeps running as a forward test, with a verdict at 250 trades or April 15, 2027, under rules written down in advance.
This is a research record, not investment advice.